Market overview and structural scope of the Arms And Ammunition Market
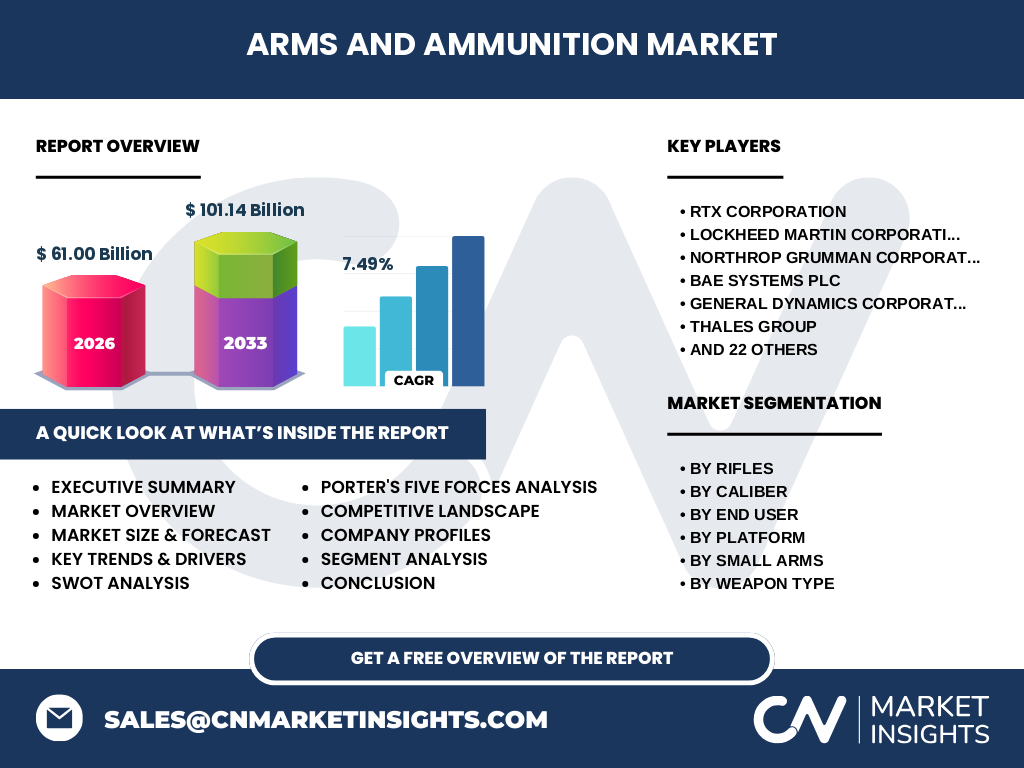
Our analysis indicates that the Arms And Ammunition Market represents a critical pillar of global defense and tactical security infrastructure. Valued at $61.00 Billion in 2026, this sector encompasses the design, engineering, and distribution of sophisticated military hardware, portable explosives, and tactical firearms overseen by strict international compliance bodies like the UN Office for Disarmament Affairs.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising geopolitical friction and modernization initiatives across military forces. However, strict export controls by bodies such as the Directorate Defense Trade Controls and complex raw material supply chains for propellants and alloy metals act as significant restraints, testing the logistical resilience of manufacturers worldwide.
The Shift Toward Smart Ballistics and Modular Weapon Systems
Industry trends reveal a rapid pivot toward digitized sighting architectures and modular weapon platforms. Prime contractors are investing heavily in IoT-enabled tracking and lightweight composite materials to enhance soldier mobility, fundamentally shifting procurement priorities away from traditional mechanical configurations.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic severely disrupted global supply chains, causing raw material shortages in copper and nitrocellulose. Despite these hurdles, accelerated government defense spending and surging civilian stockpiling fueled an aggressive post-pandemic recovery, laying the groundwork for robust long-term expansion through 2033.
Competitive Benchmarking and Market Concentration
The landscape features consolidated prime contractors like RTX Corporation and Lockheed Martin Corporation dominating high-end missile systems, alongside specialized small arms innovators like Heckler And Koch GmbH and SIG Sauer GmbH & Co. KG. Strategic M&A activity remains high as firms seek to secure supply chain dominance.
Executive Summary of Key Findings
This comprehensive report highlights a projected market expansion to $101.14 Billion by 2033, representing a robust CAGR of 7.49% from 2027. Increased defense budgets and modernization programs across NATO allies create high-conviction opportunities for investors targeting advanced tactical systems.
Market Forecast Analysis from 2027 to 2033
Driven by persistent regional conflicts and defense budget expansions, the market is set to surge from its 2026 baseline. Our forecasts indicate that precision-guided munitions and small caliber ammunition will capture the lion's share of new capital allocation during this forecast window.
Segmentation Analysis by Platform, Caliber, and End User
Market segmentation spans across Rifles, Calibers, End Users, Platforms, and Weapon Types. Military and defense forces drive land-based and air-based platform demand, while civilian and law enforcement segments support steady offtake for small caliber handguns and bolt action rifles.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, with North America leading due to high domestic defense outlays and active civilian markets. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, fueled by territorial tensions and extensive military modernization programs in nations like India and Taiwan.
In-Depth Regional Review of High-Growth Geographies
European markets are experiencing unprecedented funding spikes driven by regional security frameworks and increased interoperability mandates. Concurrently, Middle Eastern procurement is heavily weighted toward advanced portable explosives and naval defense platforms to secure critical maritime trade chokepoints.
Strategic Positioning of Leading Industry Players
Industry leaders maintain distinct competitive moats. General Dynamics Corporation and BAE Systems plc focus on heavy land and naval platforms, while commercial giants like Smith & Wesson Brands Inc. and Glock Inc. dominate civilian and law enforcement retail channels globally.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers is moderate to high due to stringent government procurement auctions. Threat of new entrants remains remarkably low, constrained by heavy capital expenditure requirements, intense intellectual property protections, and strict regulatory licensing from defense ministries.
SWOT Analysis of the Arms And Ammunition Sector
Key strengths lie in advanced R&D capabilities and entrenched government contracts. Weaknesses include vulnerability to supply chain bottlenecks for rare earth minerals. Opportunities abound in smart weapon integration, while threats stem from shifting ESG investment mandates and tightening export regulations.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction—specifically steel, copper, and energetic chemicals—processed by specialized refiners. Components flow to prime integrators like Rheinmetall AG and Thales Group before distribution through government channels or licensed retail networks.
Investment Insights and High-Potential Growth Pockets
Investors should prioritize agile manufacturers specializing in modular small arms and loitering munitions. Companies demonstrating robust ESG compliance alongside high-margin government supply contracts offer the most attractive risk-adjusted return profiles over the next decade.
Conclusion and Strategic Takeaways for Stakeholders
The sector presents compelling growth dynamics anchored by a 7.49% CAGR. Stakeholders must embrace digital transformation, supply chain diversification, and next-generation product development to capture market share in an increasingly competitive global defense ecosystem.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived by triangulating primary stakeholder interviews with defense ministry budget allocations, trade registry data from entities like SIPRI, and secondary macroeconomic indicators to ensure high fidelity across all forecasted metrics.
Scope of the Report and Coverage Parameters
This report covers global revenue projections from 2026 to 2033, analyzing market dynamics across specified weapon types, calibers, and regional blocks. Limitations include restricted access to classified black-budget military programs and localized underground manufacturing networks.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by cross-border acquisitions, such as Czechoslovak Group a.s. (CSG) expanding its manufacturing footprint, and joint ventures focusing on automated artillery production. These moves underscore a strategic race to secure production capacity amid sustained global demand.